Forecast Correction for Environmental Risk
Bayesian quantile methods for aligning observations, retrospective products, and forecast products from different systems, with evaluation tied to the information available at each forecast origin.
Antonio De Leon Bayesian Statistics | Machine Learning | Statistical Software
I develop Bayesian methods for forecasting, uncertainty quantification, and interval estimation in dynamic data.
Current projects use climate, environmental, and energy data to study forecast correction, posterior synthesis, temporal evaluation, and reproducible statistical software.
Bayesian quantile methods for aligning observations, retrospective products, and forecast products from different systems, with evaluation tied to the information available at each forecast origin.
Extended dynamic quantile linear models with MCMC, Laplace-delta variational Bayes, diagnostics, forecasting, and posterior predictive synthesis.
Bayesian quantile forecasting with fixed nonlinear recurrent features, shrinkage priors, simulation studies, multi-quantile reporting, and held-out forecast comparisons.
MTI work separates fixed-content and tolerance-interval targets from regression and dynamic-model extensions, with generalized-Bayes computation as the common thread.
Best Poster Prize
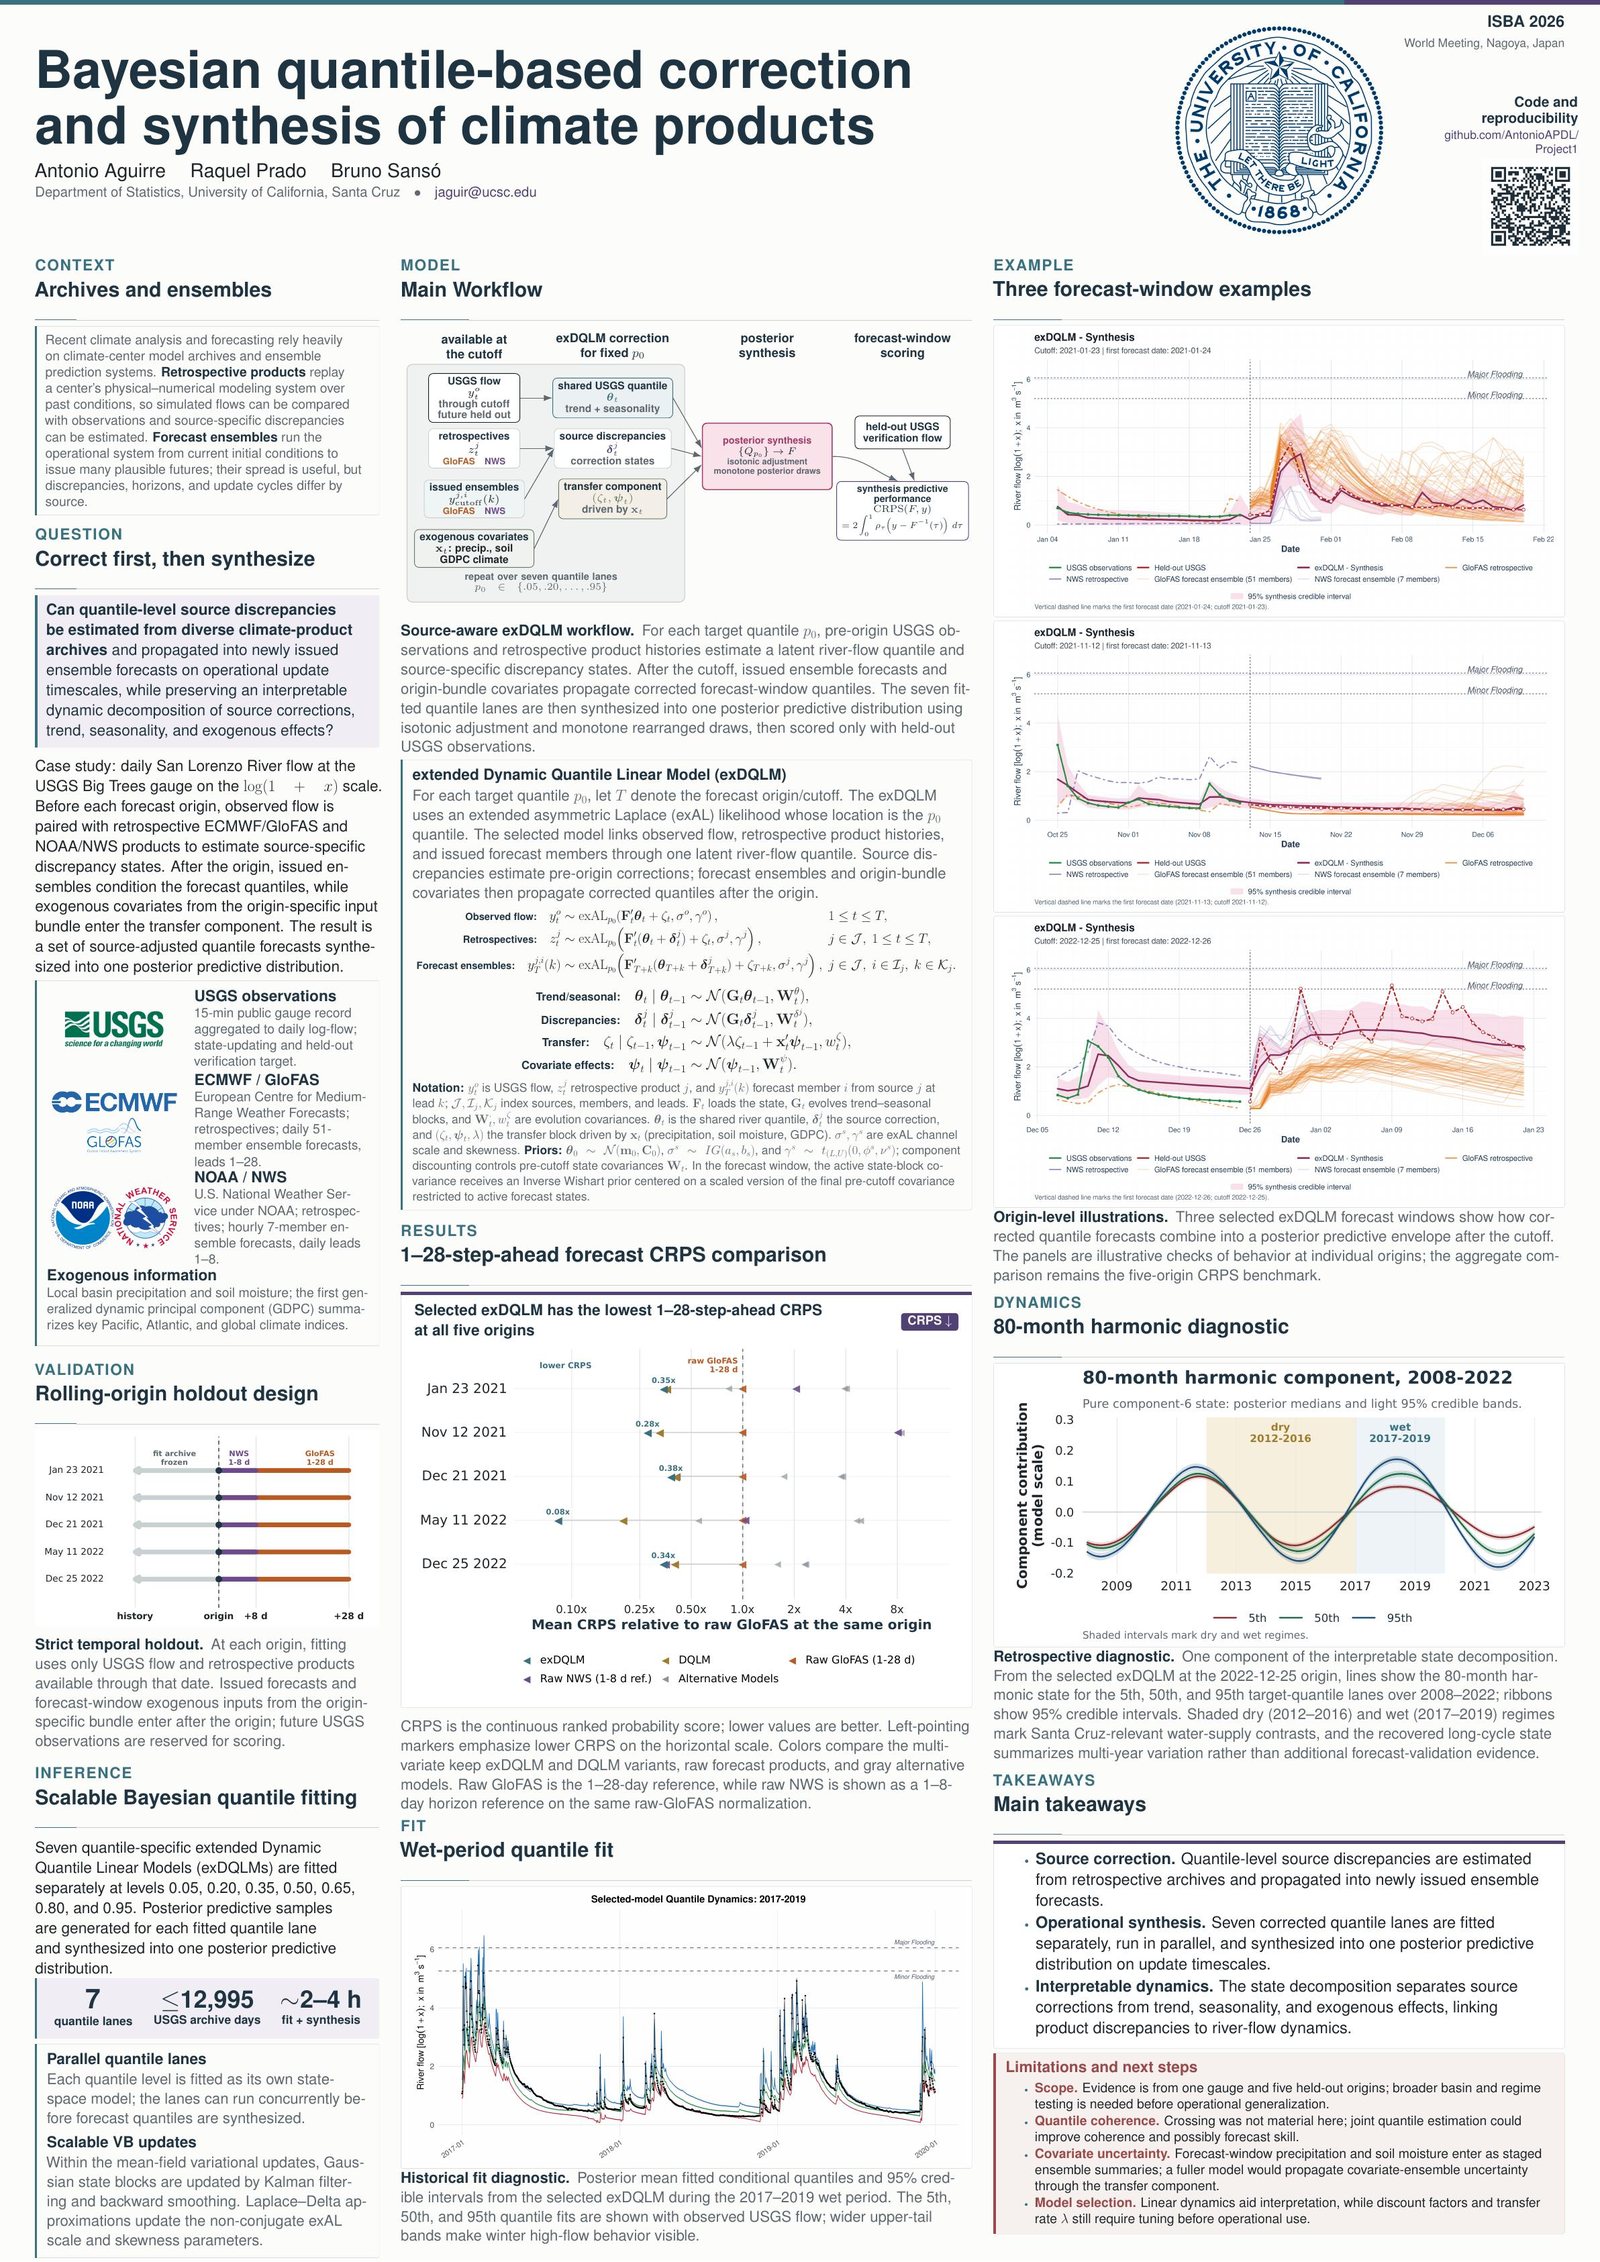
My poster Bayesian quantile-based correction and synthesis of climate products received a Best Poster Prize at the ISBA 2026 World Meeting in Nagoya, Japan. The work presents a Bayesian quantile workflow for correcting forecast products and synthesizing corrected quantile forecasts into a posterior predictive distribution. The case study uses local environmental observations and NOAA/NWS forecast guidance near Big Trees.
Package source, manuscript repositories, and selected implementation examples are listed on the Software page. Each item is labeled by release or manuscript status.